Stamp Duty & Registration Charges in Karnataka
Stamp duty and registration charges in Karnataka commonly total about 7.6% for an urban property sale in the 5% stamp-duty band. This includes 5% basic stamp duty, applicable additional duties and a 2% registration fee. Karnataka increased the registration fee from 1% to 2% with effect from 31 August 2025. Older estimates using 1% can therefore understate the purchase cost.
For a property assessed at ₹1 crore, an urban estimate of 7.6% gives ₹7.60 lakh in these charges. A ₹78 lakh property gives an estimate of ₹5.928 lakh. The final amount depends on the property value, deed type, local jurisdiction and any valid concession. GST, legal fees and loan charges are separate.
Karnataka Stamp Duty Rates for Apartment Purchases
Karnataka provides lower basic stamp-duty rates for the first sale of eligible flats or apartments within specified value limits. These concessions do not automatically apply to plots, independent houses or resale homes. “First sale” describes the property transaction, not whether the buyer has owned a home before.
| Eligible First-Sale Flat or Apartment Value | Basic Stamp Duty |
|---|---|
| Up to ₹20 lakh | 2% |
| Above ₹20 lakh and up to ₹45 lakh | 3% |
| Above ₹45 lakh | 5% |
Additional duties and registration fees are charged separately. The concession must be checked against the deed and applicable valuation. A low advertised price alone does not establish eligibility.
Karnataka Registration Fee in 2026
The standard property registration fee covered by the August 2025 revision is ₹20 for every ₹1,000 or part thereof. This is broadly equivalent to 2% of the assessed value. The revised fee took effect on 31 August 2025. It is separate from stamp duty.
For a ₹1 crore valuation, the registration fee is ₹2 lakh. Under the former 1% rate, it would have been ₹1 lakh. The change adds ₹1 lakh to this example. Buyers should use the current fee when preparing a registration budget.
Cess and Surcharge on Karnataka Stamp Duty
The additional duties are calculated on the basic stamp duty, rather than directly at those percentages on the property price. Karnataka’s Stamp Act provides an additional duty of 10% on the applicable duty. The local-body levy is generally 2% of duty in municipal areas and 3% in panchayat areas.
In the 5% band, this gives an effective stamp-duty estimate of 5.6% in an urban area. Adding the 2% registration fee brings the total to about 7.6%. The comparable panchayat estimate is about 7.65%. The property’s jurisdiction must be confirmed before choosing the calculation.
Stamp Duty and Registration Calculation for a ₹1 Crore Property
The example below assumes an urban sale assessed at ₹1 crore, with 5% basic stamp duty. It shows each component separately. This makes it easier to distinguish the registration fee from additional stamp duties.
| Charge | Calculation | Amount |
|---|---|---|
| Basic stamp duty | 5% of ₹1 crore | ₹5,00,000 |
| Additional duty | 10% of ₹5 lakh | ₹50,000 |
| Urban local-body levy | 2% of ₹5 lakh | ₹10,000 |
| Registration fee | 2% of ₹1 crore | ₹2,00,000 |
| Estimated total | 7.6% of ₹1 crore | ₹7,60,000 |
This total excludes other service or document charges. It also excludes GST where applicable. Use the official assessment for the final payment.
Does Stamp Duty Use the Sale Price or Guidance Value?
Stamp duty is based on the applicable property valuation, not simply the amount agreed with the seller. A price below the government guidance value does not automatically reduce the duty. The declared price and official valuation must be checked together. The Stamp Act’s market-value rules govern the assessment.
For example, assume the agreed price is ₹90 lakh but the applicable assessed value is ₹1 crore. Charges may need to be calculated on ₹1 crore. At the illustrative urban 7.6% total, that is ₹7.60 lakh. Checking the valuation before signing helps avoid a budget shortfall.
Purva Heron Stamp Duty and Registration Estimate
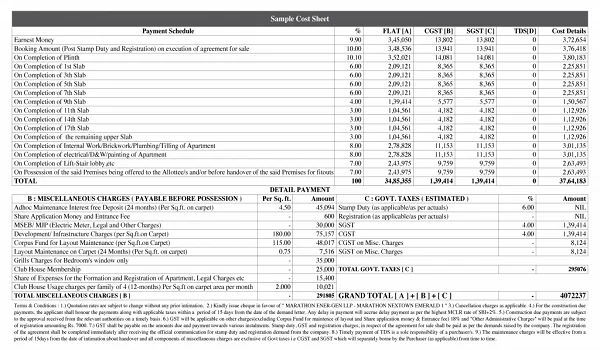
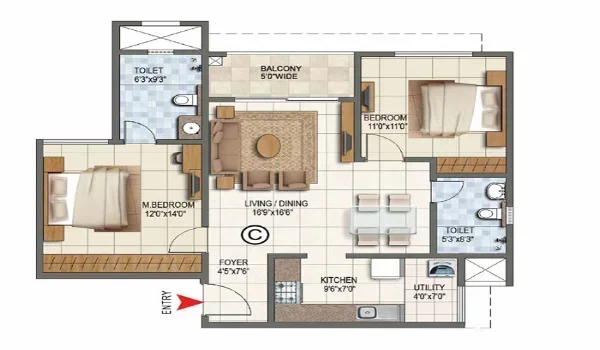
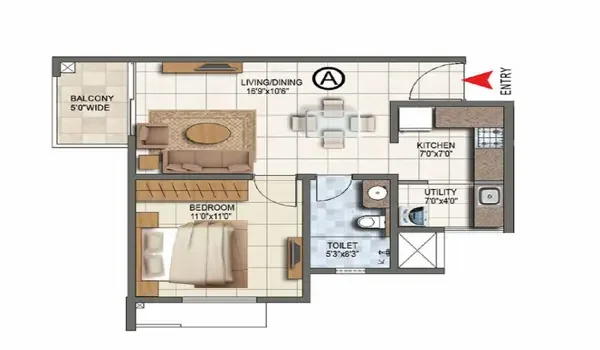
Purva Heron’s indicative starting base price is ₹78 lakh, above the ₹45 lakh first-sale apartment concession limit. A ₹1.30 crore 2 BHK is also in the 5% basic stamp-duty band. The table uses the current urban estimate of 7.6%. It assumes the stated price equals the assessed value.
| Illustrative Property Value | Basic Stamp Duty | Registration Fee | Additional Duties | Estimated Total |
|---|---|---|---|---|
| ₹78 lakh | ₹3,90,000 | ₹1,56,000 | ₹46,800 | ₹5,92,800 |
| ₹1.30 crore | ₹6,50,000 | ₹2,60,000 | ₹78,000 | ₹9,88,000 |
These are current-rate examples, not confirmed Purva Heron registration quotes. The exact site jurisdiction and assessed value need confirmation. Possession is targeted for December 2030, so rates at the time of registration may differ. GST and other purchase costs are excluded.
How to Check the Final Karnataka Registration Charges
Use Karnataka’s Kaveri services to check property valuation and prepare the registration process. The assessment needs the correct property details, location and deed type. A sale deed, gift deed and power of attorney do not share one universal fee. Check the calculation for the actual document being registered.
Keep the official payment receipts with the registered deed. Compare any amount collected by a builder or representative with the stated government charges. Legal drafting and service fees should have separate entries. A clear breakdown shows where the registration budget is going.
FAQs
The standard property fee covered by the August 2025 revision is broadly 2%. The revised rate took effect on 31 August 2025.
In the 5% stamp-duty band, an illustrative total is ₹7.60 lakh. This includes basic duty, additional duties and registration.
No. The cited concessions apply to eligible first sales of flats or apartments. They should not be applied automatically to other property types.
The 10% additional duty is calculated on the applicable basic stamp duty. It is not 10% of the property price.
Not always. The local-body levy can differ between municipal and panchayat areas.
No. GST is a separate tax where applicable. It must be budgeted separately from stamp duty and registration.