Purva Heron EMI Calculator
The Purva Heron EMI calculator estimates your monthly home loan payment using the loan amount, interest rate and repayment period. For a ₹78 lakh home, an assumed 75% loan of ₹58.50 lakh gives an EMI of about ₹50,768 at 8.5% annual interest over 20 years. The remaining ₹19.50 lakh is the buyer’s contribution towards the base price. Additional purchase charges need a separate budget.
For a ₹1.30 crore 2 BHK, the same assumptions give a ₹97.50 lakh loan and an EMI of about ₹84,613. The buyer’s contribution towards the base price would be ₹32.50 lakh. These are calculation examples, not bank offers. The lender will decide the approved loan amount, rate and tenure.
Purva Heron EMI Calculator for 1–4 BHK Homes
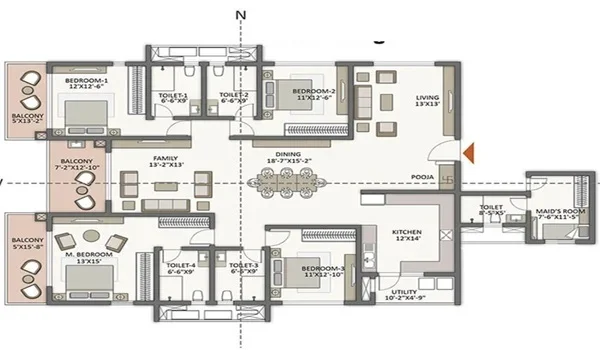
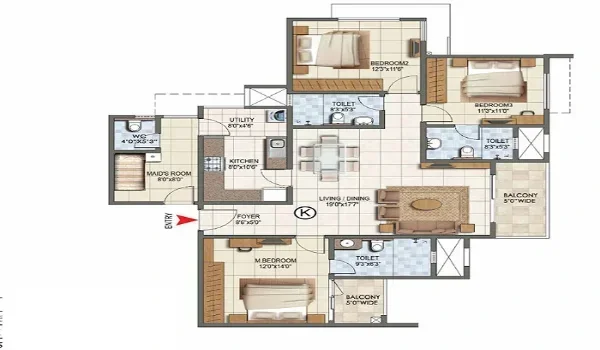
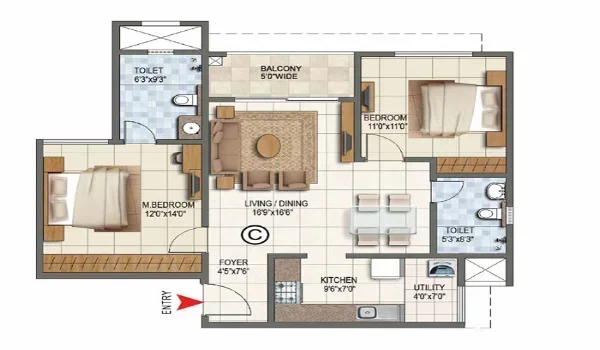
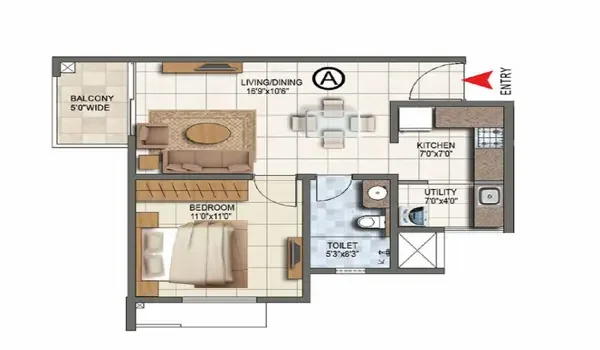
Purva Heron’s indicative starting base prices range from ₹78 lakh for a 1 BHK to ₹2.60 crore for a 4 BHK. The table below uses a loan equal to 75% of each starting price. Every example assumes 8.5% annual interest and a 20-year tenure. Actual loan terms may differ.
| Home Type | Starting Base Price | Assumed Loan (75%) | Buyer’s Share (25%) | Approximate Monthly EMI |
|---|---|---|---|---|
| 1 BHK | ₹78 lakh | ₹58.50 lakh | ₹19.50 lakh | ₹50,768 |
| 2 BHK | ₹1.30 crore | ₹97.50 lakh | ₹32.50 lakh | ₹84,613 |
| 3 BHK | ₹1.885 crore | ₹1.41375 crore | ₹47.125 lakh | ₹1,22,689 |
| 4 BHK | ₹2.60 crore | ₹1.95 crore | ₹65.00 lakh | ₹1,69,226 |
The buyer’s share shown here covers only part of the base price. It does not include taxes, registration or other charges. A larger apartment within the same home type will also cost more. Use the selected unit’s cost sheet for a closer estimate.
How to Use the Purva Heron EMI Calculator
Enter the amount you plan to borrow, rather than the full apartment price. Next, enter the annual interest rate quoted by the lender. Choose the repayment period in years or months. These three inputs determine the estimated EMI. For example, a ₹1.30 crore home with a ₹32.50 lakh contribution leaves ₹97.50 lakh to be financed. That is the loan amount used in the calculator. Changing the down payment changes this amount. Keep additional charges separate unless the lender has agreed to finance them.
Purva Heron EMI Comparison by Loan Tenure
A longer loan tenure lowers the monthly payment but increases total interest when the rate stays unchanged. For the illustrative ₹97.50 lakh loan, a 15-year tenure gives an EMI of about ₹96,012. Extending it to 25 years lowers the EMI to about ₹78,510. The lower monthly amount comes with a higher lifetime borrowing cost.
| Home Type | Starting Base Price | Assumed Loan (75%) | Buyer’s Share (25%) | Approximate Monthly EMI |
|---|---|---|---|---|
| 1 BHK | ₹78 lakh | ₹58.50 lakh | ₹19.50 lakh | ₹50,768 |
| 2 BHK | ₹1.30 crore | ₹97.50 lakh | ₹32.50 lakh | ₹84,613 |
| 3 BHK | ₹1.885 crore | ₹1.41375 crore | ₹47.125 lakh | ₹1,22,689 |
| 4 BHK | ₹2.60 crore | ₹1.95 crore | ₹65.00 lakh | ₹1,69,226 |
These figures assume the rate remains at 8.5%, with no prepayments or fees. They show why tenure matters beyond the monthly EMI. A shorter period saves interest but requires more cash each month. The chosen tenure should fit the household budget and lender eligibility.
Interest Rates and Purva Heron Monthly EMI
A small rate change can affect the EMI on a large loan. On ₹97.50 lakh over 20 years, an 8% rate gives an EMI of about ₹81,553. At 9%, the payment rises to about ₹87,723. That is a difference of roughly ₹6,170 each month.
| Illustrative Annual Rate | EMI on ₹97.50 Lakh for 20 Years |
|---|---|
| 8% | ₹81,553 |
| 8.5% | ₹84,613 |
| 9% | ₹87,723 |
These rates are used for comparison and are not current lender quotes. Enter the rate in the bank’s offer when assessing your loan. For a floating-rate loan, future changes can affect the EMI, tenure or both. Check how the lender handles those changes.
Purva Heron Down Payment and Purchase Budget
A larger down payment reduces the loan amount and monthly EMI. In the ₹1.30 crore example, contributing ₹32.50 lakh leaves a ₹97.50 lakh loan. Paying more from your own funds would reduce that borrowing need. It would also leave less cash available for other expenses.
The purchase budget should include more than the down payment. Registration, applicable taxes, additional project charges and furnishing may require separate funds. Keep an emergency reserve after these payments. An EMI that fits on paper should still leave room for regular household costs.
Purva Heron Pre-EMI During Construction
Purva Heron is at the pre-launch stage, with possession targeted for December 2030. A construction-stage loan may be released in parts rather than as one payment. Under a pre-EMI arrangement, the borrower pays interest on the amount disbursed. Some lenders also offer EMI repayment during construction, subject to the loan terms.
For example, ₹30 lakh disbursed at an assumed 8.5% rate gives a simple monthly interest estimate of ₹21,250. This is not the full EMI on the sanctioned loan. Pre-EMI interest generally rises as more funds are released. The lender’s payment schedule will establish the actual amount and start date.
Purva Heron EMI Estimate and Loan Approval
The Purva Heron EMI calculator helps compare borrowing options; it does not sanction a loan. Approval depends on the lender’s assessment of the borrower and property. Income, existing debts, age and credit history can affect the offer. Project documents also need lender review.
Purva Heron RERA approval is awaited in the current project details. No project-specific bank tie-up has been confirmed here. Obtain the lender’s written loan terms before relying on a repayment estimate. Match those terms with the project payment schedule.
FAQs
For an assumed ₹58.50 lakh loan at 8.5% over 20 years, the EMI is about ₹50,768. This uses the indicative ₹78 lakh starting base price and a 25% buyer contribution.
An assumed ₹97.50 lakh loan at 8.5% over 20 years gives an EMI of about ₹84,613. The example uses a ₹1.30 crore base price.
No. It is an illustrative rate used for these calculations. The lender will quote the applicable rate.
Yes, when the loan amount and rate stay the same. It also increases total interest if there are no prepayments.
The examples use loans based on the apartment base price only. Additional purchase costs are excluded.
Not necessarily. Payments depend on disbursement and the chosen repayment plan. The loan agreement will state whether pre-EMI or full EMI applies during construction.