GST on Under-Construction Apartments Explained
GST on under-construction apartments is generally 5% for non-affordable homes and 1% for eligible affordable homes under the current residential scheme. These are effective rates, including the standard land deduction. The scheme does not allow the builder to claim input tax credit on construction costs. Certain older projects may follow a different tax regime.
For a ₹1 crore apartment price subject to the effective 5% rate, GST adds ₹5 lakh. The price plus GST becomes ₹1.05 crore, before stamp duty, registration and other costs. A qualifying ₹40 lakh affordable apartment attracts ₹40,000 GST at 1%. The applicable rate depends on the housing category and the terms of the sale.
GST Rates on Under-Construction Apartments
The standard rates below apply to residential apartments under the post-April 2019 scheme. A home does not qualify for 1% GST just because it is small. It must meet both the carpet-area and value limits. A completed-home sale follows a separate rule.
| Apartment Purchase | GST Treatment |
|---|---|
| Eligible affordable apartment under construction | Effective 1% (without Input Tax Credit) |
| Other residential apartment under construction | Effective 5% (without Input Tax Credit) |
| Entire price received after the relevant completion or first-occupation point | No GST on the completed-building sale |
| Certain older ongoing projects | Check the tax regime chosen for the project (12% with ITC vs 5% without ITC scheme) |
The completed-sale rule uses the completion certificate, where required, or first occupation—whichever is earlier. The entire payment must be received after that point for the stated exclusion to apply.
When Does an Apartment Qualify for 1% GST?
For Bangalore, an affordable apartment must have a carpet area of no more than 60 square metres, or about 646 sq. ft. Its gross amount charged must also be no more than ₹45 lakh. Both conditions must be met. Bangalore is treated as a metropolitan city for this rule.
The ₹45 lakh test is not limited to an advertised base price. The definition includes the land share and specified charges collected by the promoter, such as parking and preferred-location charges. A home may therefore exceed the limit even if its headline price is lower. The complete cost breakdown matters.
A small apartment costing ₹78 lakh fails the value test. Its size alone cannot make it eligible for 1% GST. Under the current residential scheme, an under-construction sale of that non-affordable home would generally attract the effective 5% rate.
How to Calculate GST on an Apartment
For a simple estimate, multiply the apartment consideration by the applicable effective rate. At 5%, every ₹10 lakh adds ₹50,000 in GST. At 1%, every ₹10 lakh adds ₹10,000. Check whether the quoted price already includes GST before adding it again.
| Illustrative Apartment Price | Effective Rate | GST Amount | Price Plus GST |
|---|---|---|---|
| ₹40 lakh, if affordable criteria are met | 1% | ₹40,000 | ₹40.40 lakh |
| ₹78 lakh | 5% | ₹3.90 lakh | ₹81.90 lakh |
| ₹1 crore | 5% | ₹5 lakh | ₹1.05 crore |
| ₹1.30 crore | 5% | ₹6.50 lakh | ₹1.365 crore |
These examples exclude other charges. They assume the stated amount is subject to the effective rate and does not already include GST. The builder’s invoice should show the calculation for the actual purchase.
Does the 5% GST Rate Already Include the Land Deduction?
Yes. The commonly quoted effective 5% rate reflects the standard one-third land deduction in the residential scheme. Buyers should not deduct one-third again and then apply 5%. Doing that would understate the estimated tax.
The notified rate and taxable-value calculation produce the effective rate. Ask for an invoice that shows this clearly. For a normal budgeting example under the standard scheme, ₹1 crore multiplied by 5% gives ₹5 lakh GST.
GST on Ready-to-Move Apartments
A “ready-to-move” label alone does not settle the GST position. The important checks are the completion or first-occupation point and when the seller received payment. Where the entire price is received after the relevant point, the completed-building sale falls outside construction GST.
Paying part of the price during construction changes the analysis. Waiting until possession to pay the balance does not automatically remove GST from the earlier transaction. Check the payment history and completion documents together.
GST, Stamp Duty and Registration
GST is a different charge from stamp duty and registration. Paying GST does not replace those state charges. A home’s full purchase budget must account for each applicable cost. The quoted base price is therefore not the same as the final amount payable.
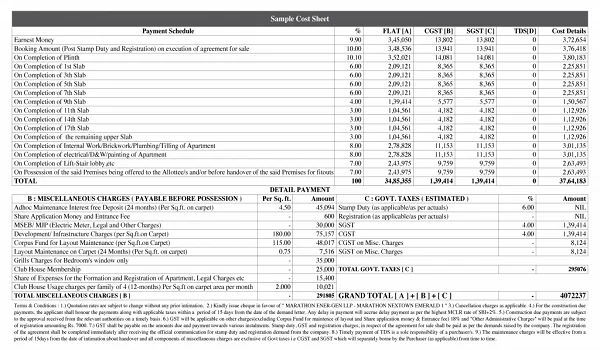
Ask for a cost sheet with separate lines for the apartment price, GST, other project charges and registration costs. Check the tax treatment of additional services rather than applying one rate to every line. Also confirm whether an advertised “all-inclusive” price includes taxes. Written figures make offers easier to compare.
GST on Purva Heron Apartments
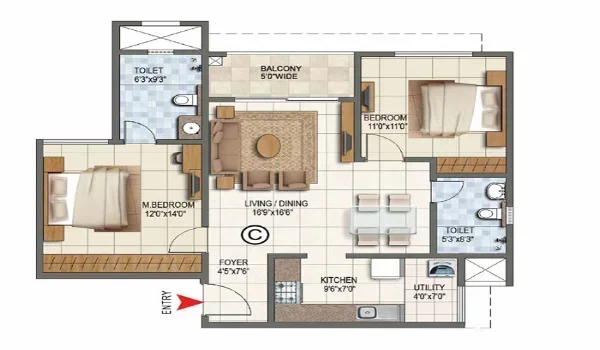
Purva Heron’s indicative starting base price is ₹78 lakh. That exceeds the ₹45 lakh affordable-housing value limit. On that basis, a qualifying under-construction residential sale would generally fall under the effective 5% scheme rather than the 1% affordable rate.
For a ₹78 lakh base price, a simple 5% estimate is ₹3.90 lakh. For a ₹1.30 crore 2 BHK base price, it is ₹6.50 lakh. These are budgeting examples, not confirmed project tax invoices. Final GST will depend on the actual sale, invoiced consideration and applicable rules.
FAQs
Under the current residential scheme, the effective rate is generally 5% for non-affordable homes and 1% for eligible affordable homes.
No. Bedroom count does not decide the rate. The apartment must meet both the carpet-area and value limits.
At the effective 5% rate, GST is ₹5 lakh. This assumes the ₹1 crore price excludes GST.
No. A completed-building sale can fall outside construction GST when the entire price is received after the relevant completion or first-occupation point.
No. The effective 5% rate already reflects the standard land deduction.
No. They are separate charges and need to be included separately in the purchase budget.